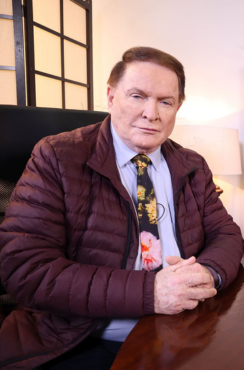
Prof. Raymond Parsons
The 2026 Medium-Term Budget is a realistic, positive and credible approach to a still challenging economic and fiscal situation given the changed global and domestic economic circumstances since the beginning of 2026.
This is the view of Prof. Raymond Parsons, economist from the North-West University (NWU) Business School.
Finance Minister Enoch Godongwana presented the important 2026 Medium Term Budget Policy Statement (MTBPS) to Parliament on 21 October.
Prof. Parsons says the broad message of the MTBPS was confidence-building. “It confirmed that, despite the global energy crisis, the recent modest economic recovery had been disrupted and delayed, rather than definitively derailed.”
He says the MTBPS reaffirmed the commitment by South Africa to stabilising debt ratios and protecting the primary budget surplus that provides the predictability that bond markets and credit rating agencies require.
“Yet while the primary surplus represents a commendable milestone in fiscal constraints, it now serves more as a defensive shield against a tougher economic climate than as a springboard for much stronger inclusive growth.”
According to Prof. Parsons, positive aspects of the Medium-Term Budget therefore included its emphasis on infrastructure development, local government and broader partnerships with the private sector.
“In particular, the attention given to support municipalities in building capacity, strengthening governance and aligning local budgets with developmental priorities has loomed large in the MTBPS.”
The latest RMB/BER business confidence index saw the local government elections on 4 November as key to boosting confidence for the rest of the year, but flagged concerns about municipal service delivery, poor infrastructure and policy uncertainty as important determinants.
Prof. Parsons says although fiscal discipline must stabilise the public debt, only a much higher job-rich growth outlook can meaningfully reduce it. “The reduced GDP growth forecasts in the MTBPS for 2026 and beyond are therefore a concern. Breaking out of the narrow 1–2% growth corridor now requires an uncompromising pivot to supply-side reform measures, even if they involve structural reform risk.”
He explains that effective reform implementation requires the policy to throw its weight behind a clearer, assertive timetable for the implementation of key reforms.
“The decision to provide business and consumers with further temporary relief from higher fuel costs is welcome, especially as windfall revenue has made this possible. The September 2026 CPI figures confirm the continued role of rising transport costs and fuel price pressures.”
Prof. Parsons points out that, nonetheless, it remains essential that the overdue commitment to review and streamline the existing formula for fixing fuel prices monthly should be expedited to create more future flexibility regarding the fuel price mechanism.
He says that, looking ahead to the main budget in February 2027, the fiscal policy must continue to act as a catalyst, shifting the focus from stability to faster job-rich growth.
“Although structural reforms are moving in a positive direction, the MTBPS recognises that the economy is still growing far too slowly. Weak growth will undermine the fiscal trajectory. What South Africa now needs from the right policies, including help from future fiscal policy, is a GDP growth rate that outpaces interest spending and debt ratios,” he concludes.


